CLIENT: Investment Firm

A credible and defensible valuation to support a minority equity buyout in a wind farm operation, requiring enhancement of the forecast model and preparation of a DCF-based valuation report.
man writing on a tablet
Key Insights

We reviewed and audited the forecast model provided by the majority partner, identifying errors and discrepancies, and refining the model for integration into a robust DCF valuation.

We collaborated with management to validate key valuation inputs, including EBITDA normalization adjustments, end-of-life asset salvage values, reclamation cost obligations, and deferred tax liabilities, while also determining the fair market value of the operating assets as at the valuation date.

We triangulated the DCF-based valuation conclusion by cross-referencing it with the adjusted book value approach, comparable public company trading multiples, and precedent transaction benchmarks to validate the reasonableness of the implied valuation metrics.

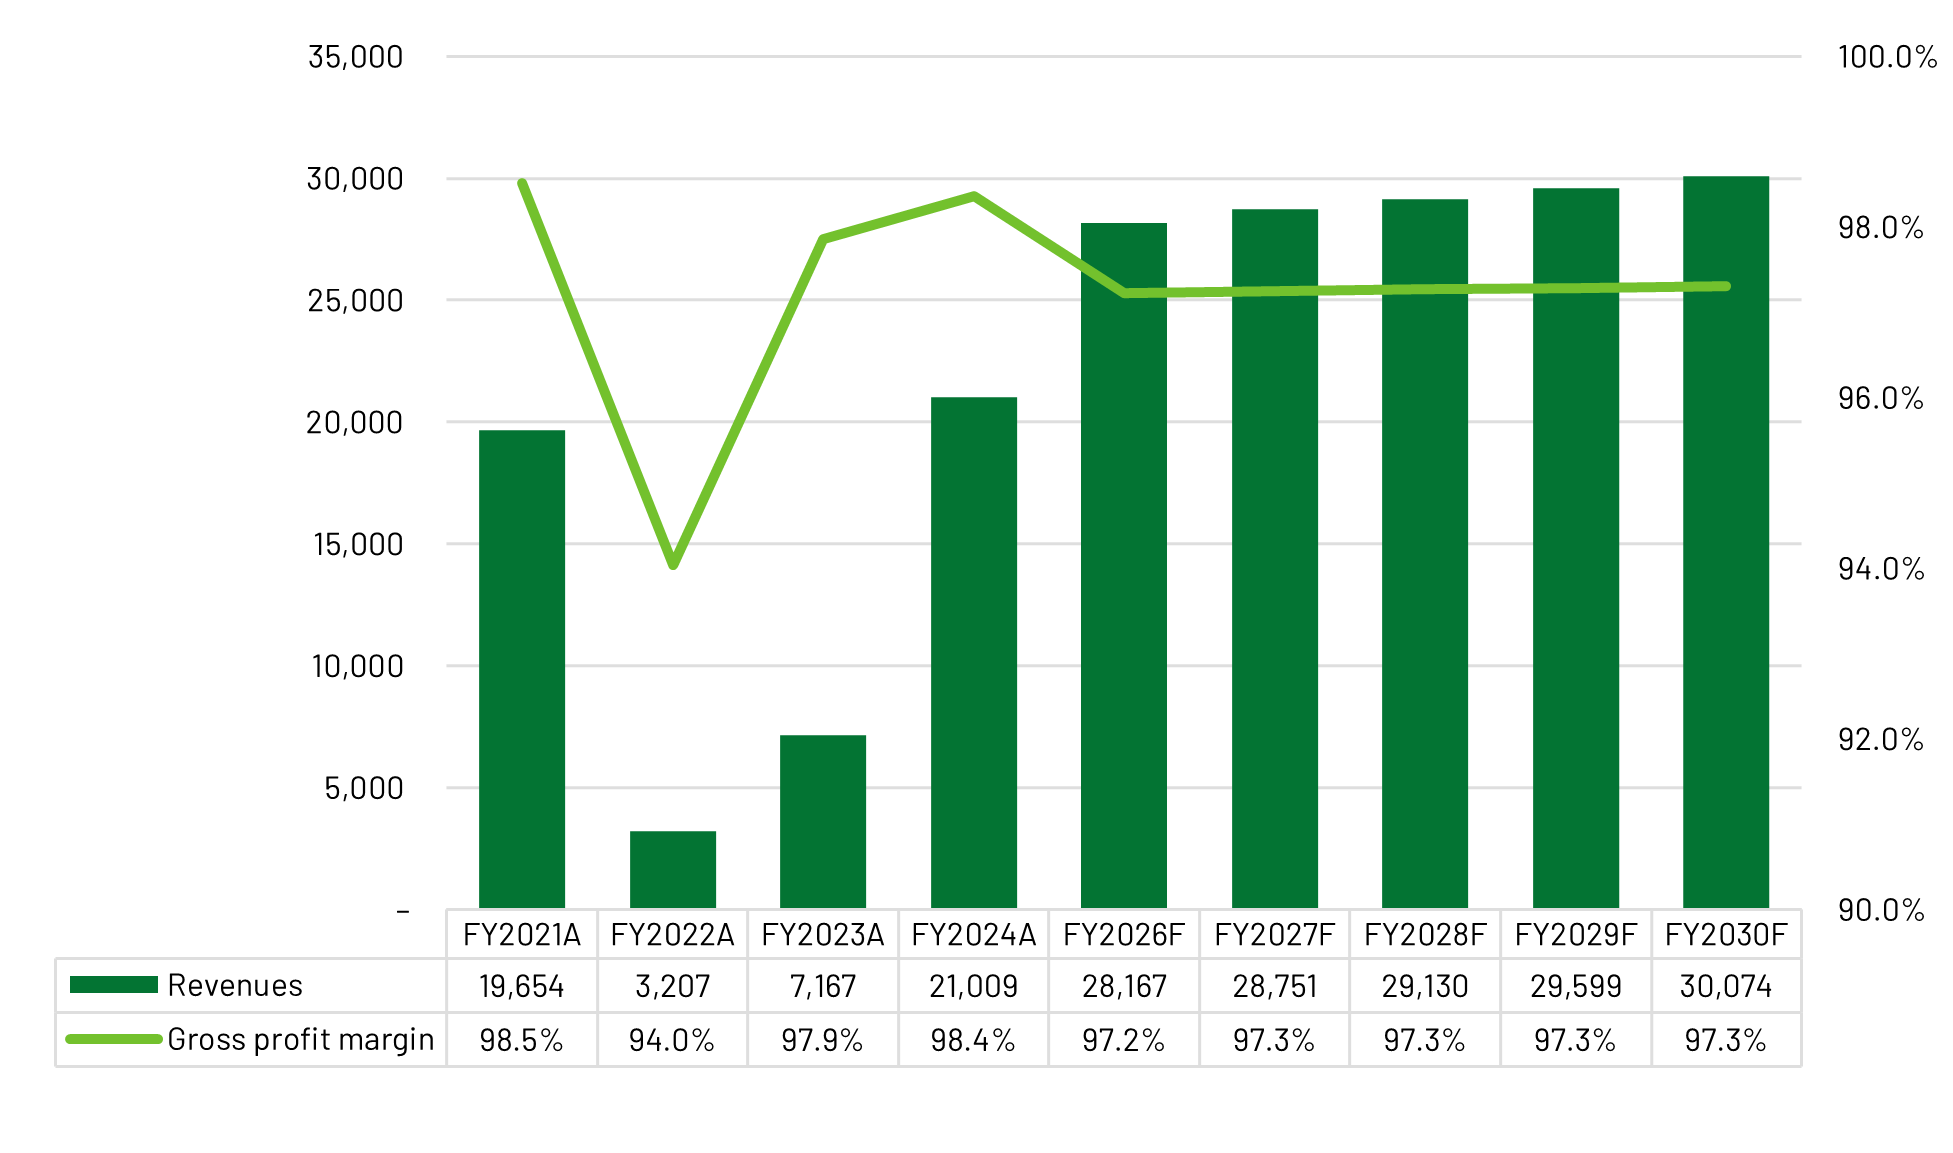
Historical and Forecasted Revenues and Gross Profit Margin
Latest Case Studies
  • Sell-Side Quality of Earnings
    • August 26, 2026

    A B2B distributor selling to major retailers in the U.S. engaged Sapling to perform a sell-side Quality of Earnings review to support the planned sale of the business. The engagement focused on reconstructing and validating historical financial performance using transaction-level data, bank activity, inventory records,...

  • Project Pipeline and 3-Statement Model
    • August 3, 2026

    A heavy civil construction contractor running operations across several entities asked Sapling to build a management model that delivers private equity-level, best-in-class budgeting and scenario planning. The goal was a 3-statement model and dashboard that builds up from the project pipeline, so the team could...